Ford Motor Company has surpassed Wall Street’s first-quarter earnings predictions, primarily driven by hearty sales from its trucks and other commercial vehicles, offsetting the losses incurred by its electric vehicle unit.
Despite not altering its 2024 earnings outlook, which states an adjusted Earnings Before Interest and Taxes (EBIT) of $10 billion to $12 billion, the automotive giant reduced its capital expenditure expectations marginally. Simultaneously, it enhanced its adjusted free cash flow projection for the current year.
Ford now anticipates generating an adjusted free cash flow of $6.5 billion to $7.5 billion, displaying an increase from the former expectation of $6 billion to $7 billion. The forecast for capital expenditure presently stands at $8 billion to $9 billion — a concise figure compared to the initially expected range of $8 billion to $9.5 billion.
John Lawler, Ford’s CFO, labeled the quarter as “solid”, reassuring stakeholders that the automaker is all set to accomplish its guidance as previously declared. Despite topping earnings estimates, the revenue generated by the automotive segment of the company fell marginally short of Wall Street expectations.
The results for Ford’s first quarter, in contrast to Wall Street’s anticipations, were as follows: earnings per share stood at 49 cents (adjusted) against the expected 42 cents and automotive revenue at $39.89 billion in comparison to the projected $40.10 billion.
Ford’s all-inclusive revenue for the first quarter, which encapsulates its credit business, exhibited a year-on-year increase of around 3% amounting to $42.78 billion. The period’s net income was $1.33 billion, or 33 cents per share, compared to $1.76 billion, or 44 cents, recorded a year earlier. The Adjusted EBIT declined by 18% year over year to $2.76 billion, or 49 cents per share.
Ford’s conventional business, Ford Blue, reported adjusted earnings that were down by 66% year-on-year at $905 million. However, Ford Pro, its commercial business, earned $3.01 billion, showing a significant increase of 120% compared to Q1 of the previous year. Unfortunately, Ford’s electric vehicle unit, Model e, reported a first-quarter loss of $1.32 billion.
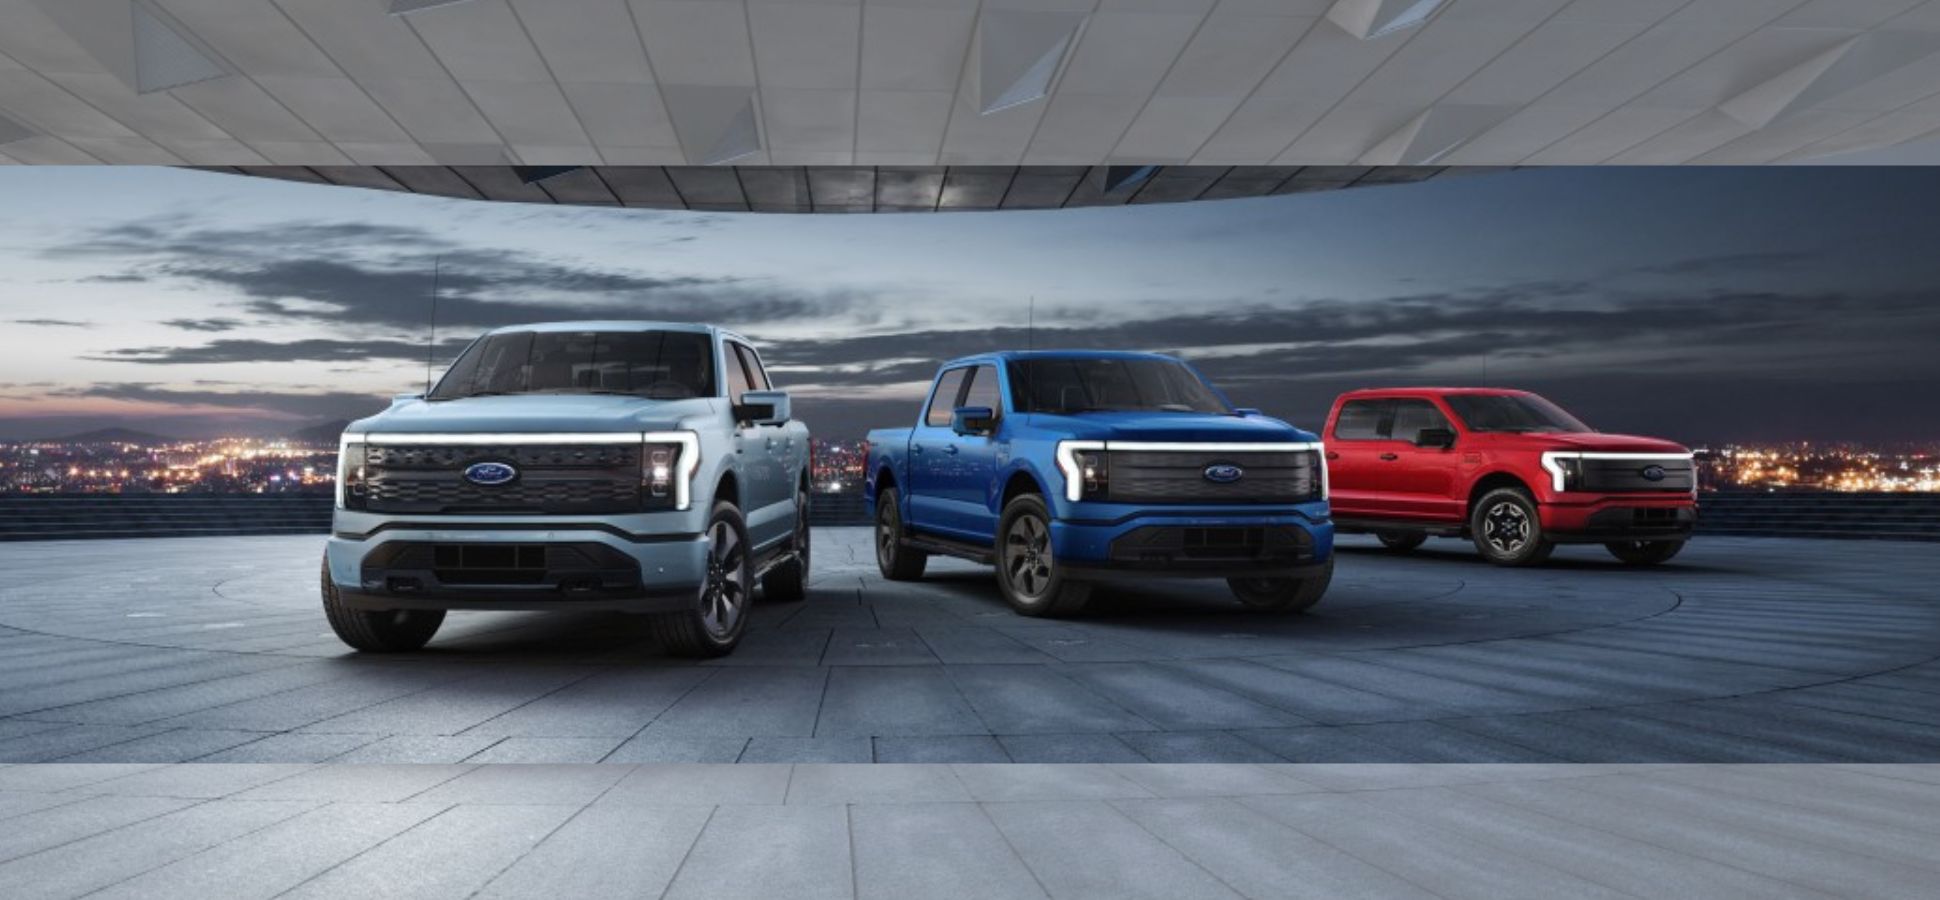
One significant factor behind Ford Blue’s notable decline was the delay in the company’s revamped F-150 pickup’s launch. The company had halted most of the quarter to tackle undisclosed quality issues.
Ford’s CEO, Jim Farley, disclosed that the company managed to avert nearly 12 recalls by conducting additional quality checks during the stop-shipment period. These interventions significantly reduced the company’s warranty cost. Farley reiterated his faith in the new process, stating that it would lead to few recalls and lower warranty costs in the long term.
Historically, Ford has grappled with inflated warranty costs, including a whopping $1.9 billion in 2023, which impacted its earnings considerably. As a result of production costs, quality issues, and other operational inefficiencies, Ford has faced an annual disadvantage of $7 billion to $8 billion compared to ordinary rivals.
Finally, Ford’s first-quarter results reporting coincided with strong first-quarter results from its local competitor, General Motors, which enhanced its full-year guidance just a day before.