The dusk of the traditional department store bonus scheme is about to take a hit. Established giants such as Macy’s and Kohl’s relied heavily on store-branded credit cards, which lent them an extra boost in revenues. However, an upcoming rule change by the Consumer Financial Protection Bureau (CFPB), effective May 14, might mean lost earnings for these retailers. The new rule caps late fees for overdue customers at $8, down from the industry average of approximately $32.
While this amendment primarily benefits customers with pending balances, the other side of the coin shows how it could harm retailers’ lucrative business models. This reduction in income can significantly impact specialty retailers like Gap, whose store cards are essential to their operations. Even more troubling, department stores stand to suffer the most, as they are already grappling with revenue pressure.
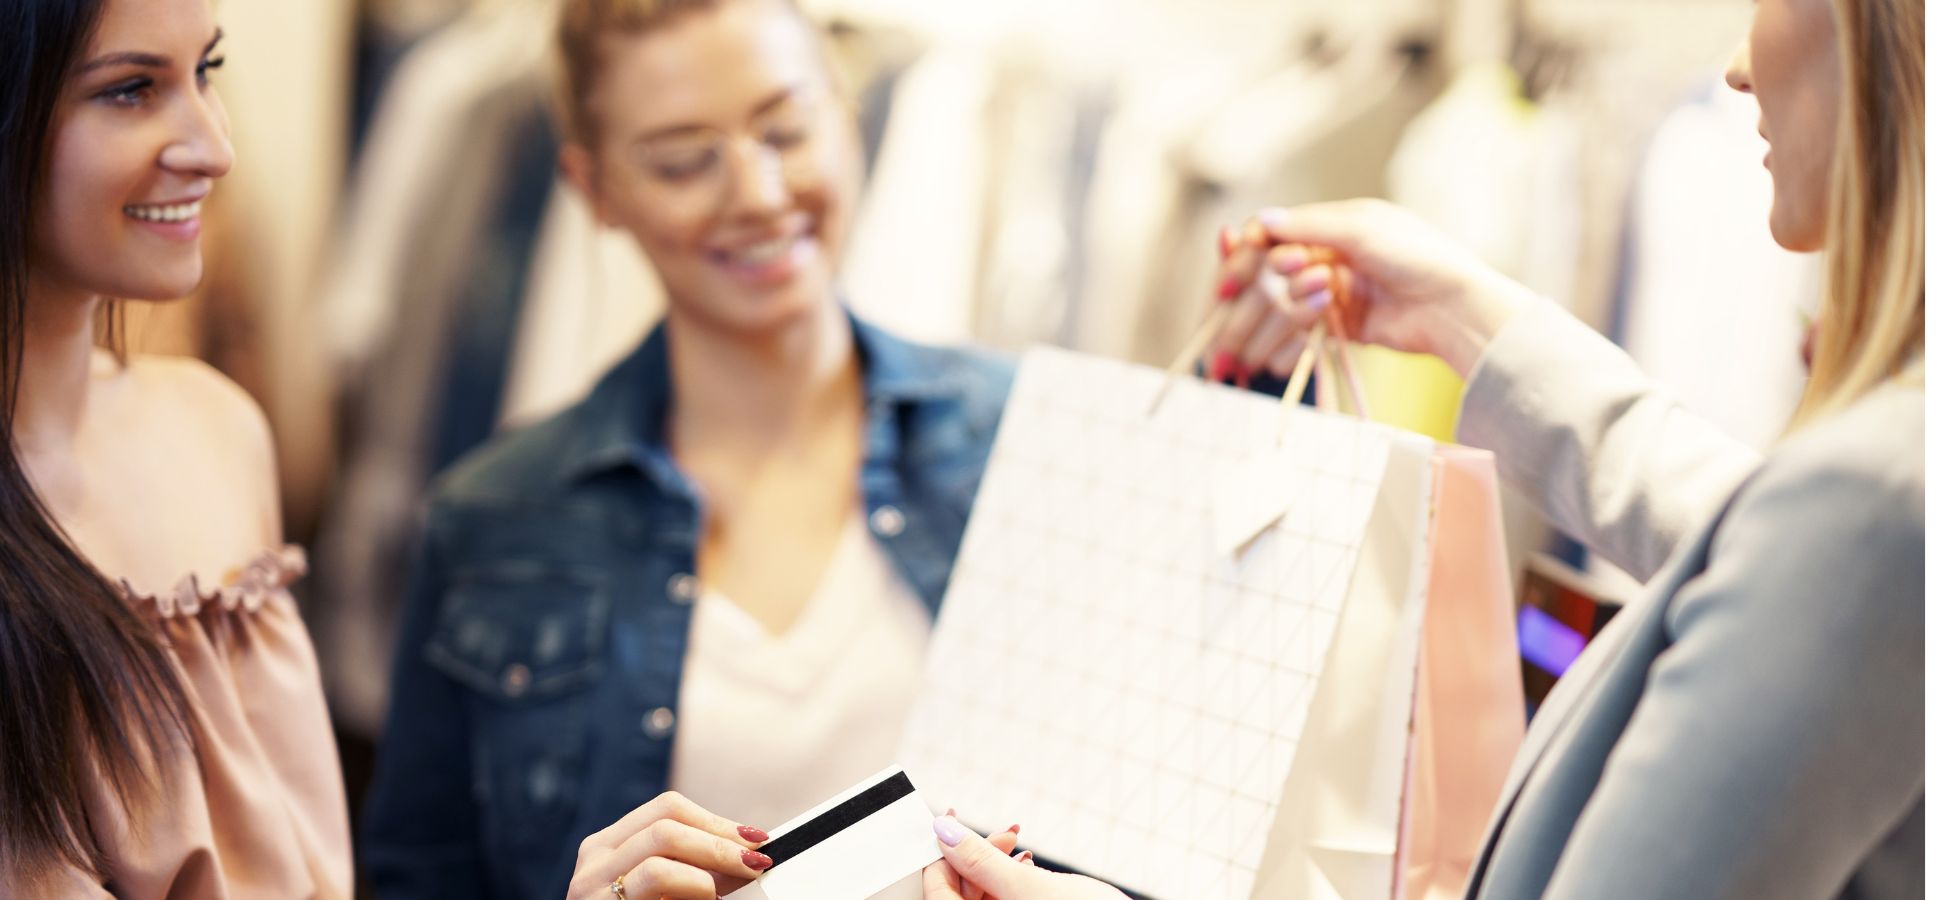
Implemented through affiliate banks and financial service companies such as TD Bank, Capital One, and Synchrony Financial, store-branded credit cards stimulate purchases and provide retailers with clear insights into customer shopping habits. Despite being an almost cost-free operation, these credit cards also function as a persistent advertisement for the retailer brand. However, ongoing changes in consumer shopping habits, interest rate environment, and the impending late fee ruling by the CFPB are threatening the survival of this revenue stream.
The use of store-branded credit cards represents a small portion of these retailers’ net sales, but the impact of this change can be profound. Other means of payment entities such as ‘buy now, pay later’, enjoy a growing popularity, totaling a hefty $19.2 billion in online purchases in Q1 of this year, a 12.3% increase YoY.
Moreover, in a high-interest-rate environment, enticing customers to sign up for and use store-specific cards might be more of a challenge. Comparative interest rates for retailer credit cards stand around 29.33% on average, far above the US credit card average of 20.75%. These factors, combined with the inevitable decrease in late-fee revenue, spell out the shrinking profitability of credit cards for retailers.
Macy’s, Nordstrom, and Kohl’s have all reported significant credit card revenues totaling hundreds of millions for fiscal 2023, despite the lack of disclosure concerning the proportion of this revenue derived from late fees. Each of these companies have reported YoY declines in credit card revenue for the recent fiscal year, affected by reduced discretionary spending and normalizing credit practices.
Despite the imminent hurdle presented by the CFPB rule, retailers are outlining strategies to counteract it, including creating co-branded credit cards and focusing on customer loyalty. Retailer strategies include Macy’s collaboration with Citi to counteract the late fee ruling and Kohl’s push for a transition to co-branded Capital One cards, which can be used across a broader array of purchases.
Regardless of the challenges, retailers are not giving up the credit card business just yet, as it tends to boost customer loyalty and spending. For instance, Kohl’s credit card customers spend six times more annually than non-loyalty shoppers. The retailer also hopes to profit an incremental credit revenue between $250 million and $300 million annually by 2025 through its co-branded card. However, the survival of the store-branded credit card, an erstwhile beacon of profitability, will be the true telltale of future retail business models.