
In the rapidly evolving financial landscape of 2024, avoiding common financial pitfalls is more critical than ever. Whether you’re just starting your financial journey or looking to refine your strategies, understanding these top nine financial mistakes can help you achieve greater financial stability and success. Let’s dive into these crucial areas and how to steer clear of them.
9. Lack of Insurance Coverage
Insurance is a safety net that protects you from unforeseen financial burdens. Many people underestimate the importance of having adequate insurance coverage, whether it’s for health, car, or home. Without proper insurance, a single incident could lead to a financial deluge, wiping out your savings and plunging you into debt.
Key Tips:
- Evaluate your insurance needs regularly.
- Ensure you have comprehensive coverage for health, car, and home.
- Avoid skimping on insurance to save money in the short term, as it could lead to a debt disaster in the long run.
8. Neglecting an Emergency Fund
An emergency fund acts as a financial shock absorber during unexpected events like medical emergencies or job loss. Despite its importance, many overlook building this crucial safety net.
Key Tips:
- Aim to save three to six months’ worth of living expenses.
- Set up automatic deductions to your savings account to build this fund gradually.
- Resist the temptation to dip into this fund for non-emergencies.
7. Poor Tax Planning
Taxes can significantly impact your financial health if not managed correctly. Many people wait until the last minute to handle their taxes, leading to rushed decisions and potential penalties.
Key Tips:
- Plan for taxes throughout the year, not just at tax season.
- Consider hiring a tax professional to help with tax planning and maximize deductions.
- Keep detailed records of all financial transactions to simplify the tax filing process.
6. Mismanagement of Credit Cards
Credit cards are convenient but can lead to financial trouble if mismanaged. One common mistake is paying only the minimum balance, which can result in mounting interest and prolonged debt.
Key Tips:
- Always try to pay off more than the minimum balance each month.
- Keep track of your spending to avoid exceeding your budget.
- Use credit cards wisely and consider them a tool for building credit rather than a means for extra spending.
5. Undefined Financial Goals
Without clear financial goals, it’s easy to fall into poor financial habits. Setting specific, achievable goals gives you a roadmap for your financial journey.
Key Tips:
- Define your financial goals, such as saving for a down payment on a house, a dream vacation, or a comfortable retirement.
- Break down large goals into smaller, manageable steps.
- Regularly review and adjust your goals as your financial situation changes.
4. Ignoring Your Credit Score
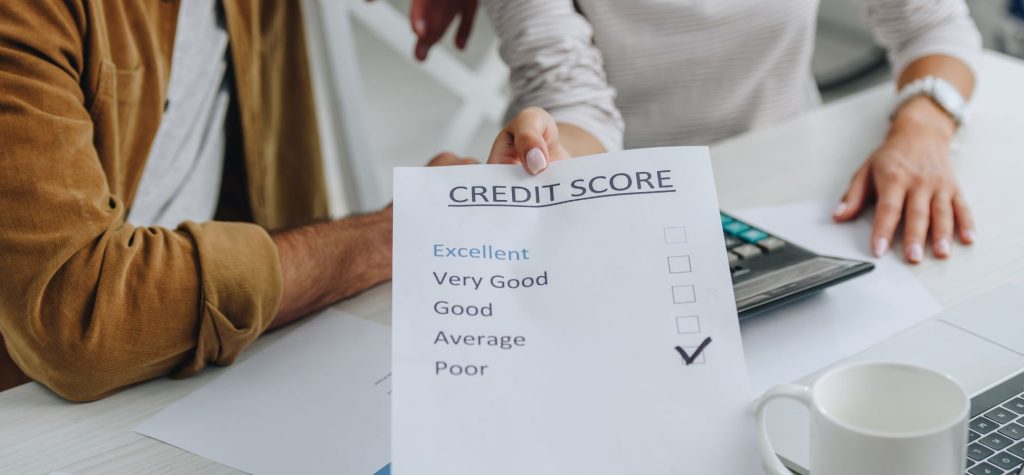
Your credit score is a crucial component of your financial health. Ignoring it can lead to higher interest rates and difficulty obtaining loans.
Key Tips:
- Check your credit score regularly to monitor for inaccuracies.
- Consider hiring an accountant to help improve your credit score.
- Take steps to improve your score, such as paying off debts and keeping credit card balances low.
3. Not Investing Wisely
Leaving your money idle in a savings account means missing out on potential growth through investing. Investing can help your money grow and work for you over time.
Key Tips:
- Educate yourself on different investment options and strategies.
- Join an investing group for education and networking opportunities.
- Diversify your investments to spread risk and increase potential returns.
2. Lack of a Budget
A budget is essential for managing your finances effectively. Without a budget, it’s easy to overspend and lose track of where your money is going.
Key Tips:
- Use your bank statements to create a realistic budget.
- Identify and cut back on unnecessary expenses.
- Regularly review and adjust your budget to reflect changes in your financial situation.
1. Ignoring Debts
Ignoring debts can lead to serious financial consequences. It’s essential to address and manage your debts proactively.
Key Tips:
- Create a repayment plan that prioritizes high-interest debts.
- Consider hiring an accountant to help manage your debts.
- Stay committed to your repayment plan to avoid falling deeper into debt.
FAQs on Financial Mistakes
What are financial mistakes?
Financial mistakes are poor decisions or actions that negatively impact your financial health. These can include overspending, inadequate insurance coverage, ignoring debts, poor tax planning, and more. Avoiding these mistakes is crucial for achieving financial stability and long-term success.
What is your biggest financial mistake?
Your biggest financial mistake could vary depending on your situation. Common examples include not having an emergency fund, mismanaging credit card debt, and failing to invest wisely. Reflect on your financial habits and identify areas where you can improve to prevent similar mistakes in the future.
What to do when you make a financial mistake?
When you make a financial mistake, it’s important to act quickly to minimize the damage. Here are steps to take:
- Acknowledge the mistake and understand its impact.
- Develop a plan to address the issue, such as creating a budget or repayment plan.
- Seek professional advice if needed, such as hiring an accountant or financial advisor.
- Learn from the mistake to avoid repeating it in the future.
Avoiding these top nine financial mistakes in 2024 can help you achieve financial freedom and stability. By taking proactive steps, such as setting clear financial goals, managing debts, and investing wisely, you can build a solid financial foundation. Stay informed, plan ahead, and make smart financial decisions to ensure a prosperous future. Subscribe to the Entrepreneur Daily newsletter for more tips and insights on navigating your financial journey.


