In today’s financial landscape, credit plays a pivotal role in shaping our financial opportunities. From buying a home to securing a loan for higher education, credit scores are a critical factor that lenders and financial institutions use to assess an individual’s creditworthiness. This article dives deep into the world of credit, offering insights into the importance of credit scores, strategies for improving credit, and the far-reaching effects of credit on borrowing and financial decision-making.
The Significance of Credit Scores
What is a Credit Score?

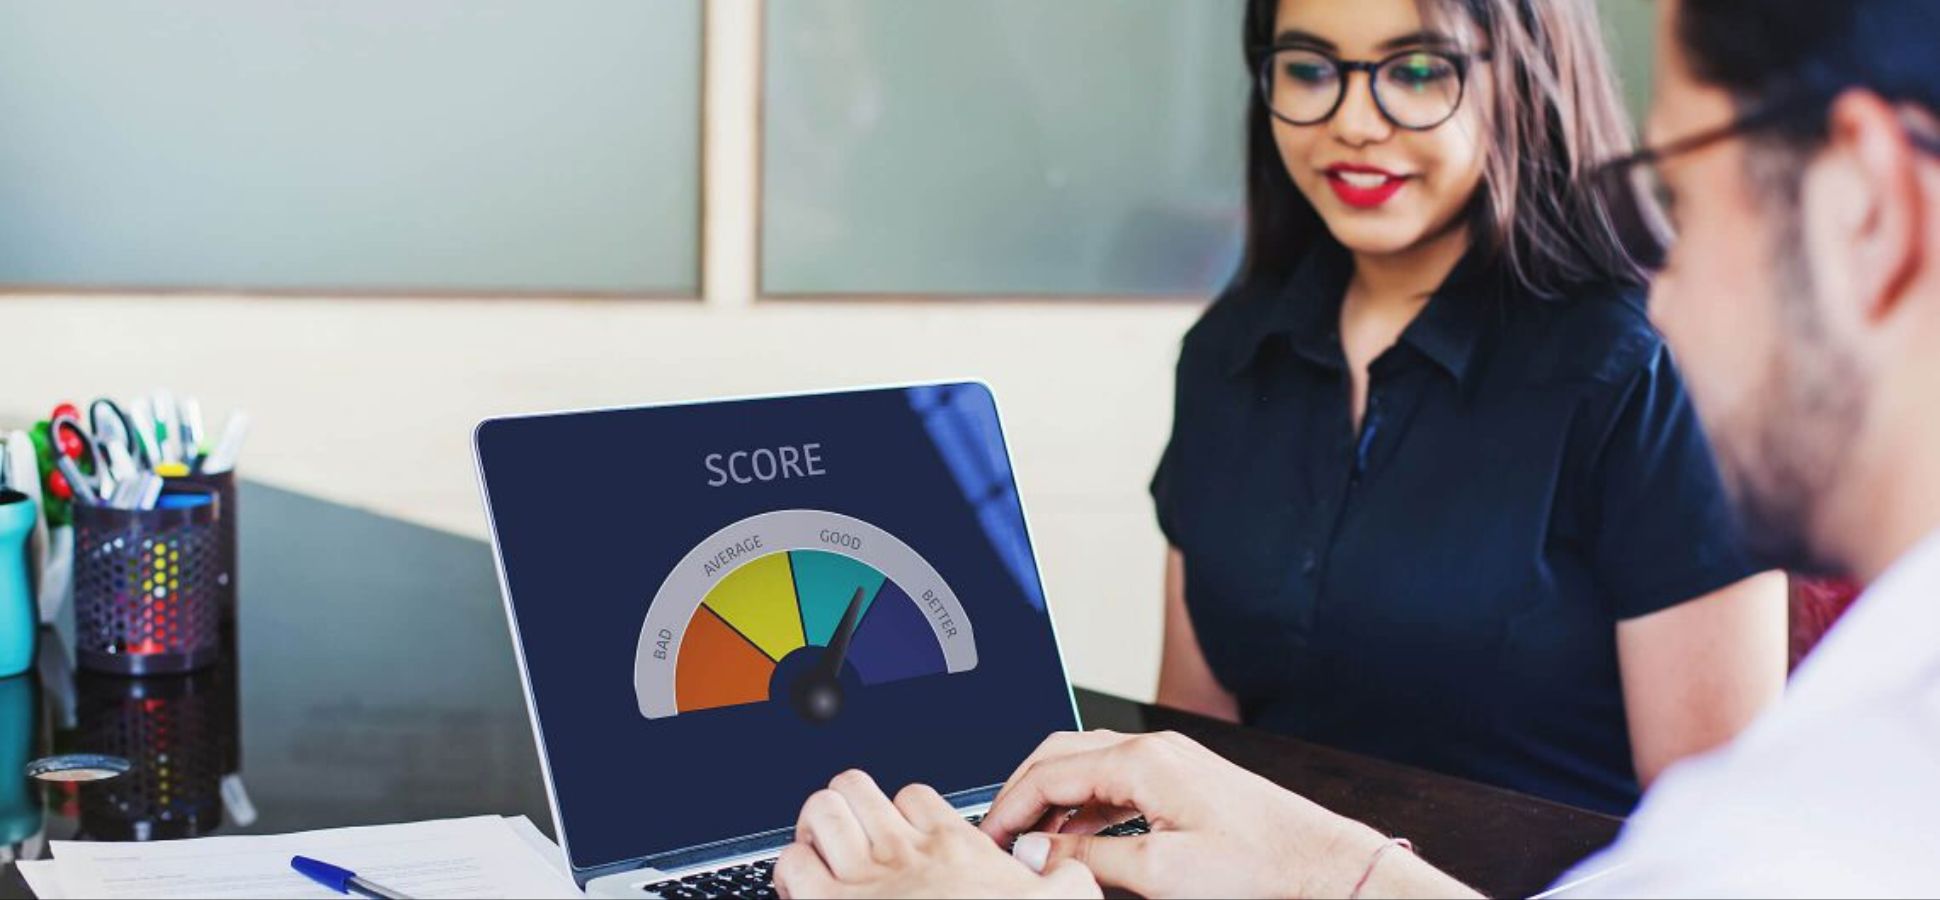
A credit score is a numerical representation of an individual’s creditworthiness. Ranging from 300 to 850, this score is derived from various financial factors and reflects a person’s ability to manage credit responsibly. The higher the score, the more favorable lending terms and interest rates one can secure.
Components of a Credit Score
A credit score is determined by several key components:
- Payment History: Timely payment of bills, loans, and credit card balances accounts for a significant portion of your credit score.
- Credit Utilization: The ratio of your credit card balances to your credit limits affects your score. A lower utilization rate demonstrates responsible credit usage.
- Length of Credit History: A longer credit history generally indicates a more stable financial track record.
- Types of Credit: Having a mix of credit types (e.g., credit cards, mortgages, installment loans) can positively influence your score.
- New Credit: Opening multiple new credit accounts in a short period can temporarily lower your score.
Improving Your Credit Score
Improving your credit score requires discipline and patience. By following these strategies, you can gradually enhance your creditworthiness:
1. Check Your Credit Report
Regularly review your credit report for errors or inaccuracies. Dispute any discrepancies with the credit bureau to ensure an accurate representation of your credit history.
2. Pay Bills on Time
Consistently paying your bills on time is one of the most impactful ways to boost your credit score. Set up reminders or automatic payments to avoid missed due dates.
3. Reduce Credit Card Balances
Lowering your credit card balances can significantly improve your credit utilization ratio. Aim to keep your balances below 30% of your credit limit. For UK readers, a responsibly managed credit card can help you build and improve your credit score, and this UK‑focused guide explains card types, eligibility checks, fees, and consumer protections.
4. Avoid Opening Unnecessary Accounts
While having a diverse credit mix is beneficial, refrain from opening new accounts solely for the purpose of boosting your credit score. Each new application can result in a small credit score decrease.
5. Maintain Older Accounts
The length of your credit history matters. Keep older accounts open, even if you don’t use them frequently, to demonstrate a long track record of responsible credit management.
6. Be Cautious with Credit Applications
When you apply for new credit, a hard inquiry is made on your credit report. Multiple hard inquiries within a short period can lower your score temporarily.
The Impact of Credit on Borrowing and Financial Decisions
1. Borrowing Opportunities
Your credit score plays a pivotal role in determining your borrowing opportunities. A higher credit score can make it easier to secure loans for major purchases, such as a car or a home, and qualify for lower interest rates.
2. Interest Rates
Lenders use your credit score to assess the risk of lending to you. A higher credit score often translates to lower interest rates, saving you money over the life of a loan.
3. Rental Applications
Even in the housing market, credit scores matter. Landlords may consider your credit score when evaluating rental applications, as it provides insights into your financial responsibility as a tenant.
4. Employment Opportunities
Certain employers might review your credit history as part of the hiring process, especially for roles that require financial responsibility. A positive credit history could potentially enhance your job prospects.
5. Utility Services
When setting up utility services (electricity, water, internet), some providers may check your credit history. A lower credit score might lead to higher security deposits.
6. Insurance Premiums
Believe it or not, your credit can impact your insurance premiums. Some insurance companies consider credit information when calculating premiums for auto or homeowner’s insurance.
7. Financial Well-being
Beyond borrowing, credit reflects your financial habits and responsibility. Good credit management can lead to a stronger overall financial well-being, offering peace of mind during unexpected expenses.
Understanding credit is a crucial aspect of modern financial literacy. From the significance of credit scores to the strategies for improving them and the far-reaching effects on borrowing and financial decisions, credit shapes various aspects of our lives. By actively managing and improving your credit, you can unlock numerous opportunities and secure more favorable financial terms.
As you navigate your financial journey, remember that credit is a tool that can work for or against you. Responsible credit management opens doors, while poor credit decisions can lead to challenges. Educate yourself, make informed choices, and take control of your financial future.
What insights have you gained from this article? How do you plan to improve your credit management or leverage your credit for better financial opportunities? Share your thoughts below!